Collateral management is our core service. We take independent control of goods pledged as security, so the bank can lend with confidence and recover with certainty. The client keeps title, VSM controls the goods, and the bank holds the security.
What the Bank Holds
| The security | Possession of the goods by VSM under the agreement, evidenced by a stock certificate in the bank’s name and monthly position reports. |
|---|---|
| The client’s position | Title stays with the client. The client cannot take delivery, sell or move the stock without the bank’s written release order. |
| Where the goods sit | The client’s premises under VSM control, or a partner warehouse where the premises are unsuitable. |
| Insurance | All risk cover on the goods and professional indemnity on VSM, with the bank named loss payee. |
| Cover | Three to five times the loan value plus bank charges, marked to the value agreed at appraisal. |
| Release | On the bank’s written order only, verified before any stock leaves the store. |
What we do
- Custody of pledged goods under a tripartite Collateral Management Agreement
- Inspection, counting and reconciliation against the bank’s security position
- Warehouse supervision for the life of the facility
- Stock and movement reports, risk alerts and exception reports
- Release only against the bank’s written authorisation
- Placement with partner warehouse operators where needed
Two Facilities, One Discipline
Custody works the same way on both. What changes is where the goods come from, how they are valued, how long the facility runs and how it is repaid.
| Import facility | Local and export facility | |
|---|---|---|
| What is financed | Goods arriving through customs: building materials, equipment, packaging, industrial inputs and other non-perishable imports. | Commodity bought in the local market or held for a contracted buyer, including coffee, grain and produce in non-perishable form. |
| How goods reach the store | Cleared by the clearing agent, then moved by VSM with its logistics partner to the agreed premises. | Collected from the supplier or aggregation point and moved to the agreed premises. |
| Basis of value | The tax value from the Uganda Revenue Authority assessment, read against the market value VSM proposes. | Market value proposed by VSM against prevailing prices, supported where available by the buyer contract. |
| Typical tenure | 90 to 120 days, matched to the sales cycle of the stock. | Set against the buyer contract or the selling season. |
| Repayment | Sales proceeds banked into the flagged account as stock is released in tranches. | Proceeds of the contracted sale, or the client’s own resources. |
Where Goods Are Held
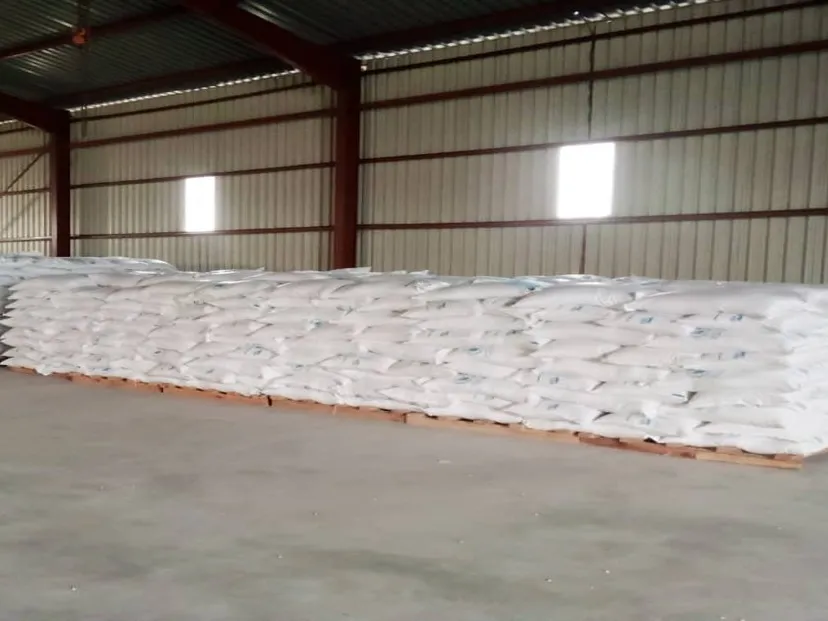
Custody runs at the client’s own premises wherever the site can be secured. Before any facility is confirmed, VSM assesses the structure, security, access control, separation of financed from unfinanced stock, and whether dual key control is practical. Where the premises cannot be secured, the goods go to a partner warehouse under the same agreement and controls. We accept non-perishable goods with a shelf life beyond six months.
What the lender gains
- Lower loss given default and stronger recovery
- The ability to lend against commodities and warehoused goods the bank could not safely hold itself
- Less fraud and stock loss
- Specialist trade and collateral capacity without building the function in-house